
Heavy Hitter
Licensed Expert (NMLS #2146417)

Veteran Lineup
In the mortgage business since 2003

MVP Status
5.0 Rating · 24 Reviews

Former Pro
7 years in the Seattle Mariners organization
Whether you're stepping up to the plate for your first home or refinancing, we'll build you a clear game plan and coach you step-by-step from application to closing.
“I'll help you cover all your bases and get you home safe.”
Licensed Expert (NMLS #2146417)
In the mortgage business since 2003
5.0 Rating · 24 Reviews
7 years in the Seattle Mariners organization
The right pitch for your situation
A flexible option for many buyers, with a range of down payment choices.
Learn more +A conventional loan isn't backed by a government agency. It follows guidelines set by Fannie Mae and Freddie Mac.
It can work for primary homes, second homes, and investment properties. Some eligible first-time buyers may qualify with as little as 3% down.
With less than 20% down, private mortgage insurance (PMI) is usually required, and it can typically be removed once you build enough equity.
Best for: borrowers with solid credit and steady income who want flexibility.
Lower down payment options with flexible credit guidelines.
Learn more +An FHA loan is insured by the Federal Housing Administration, which lets lenders offer more flexible credit guidelines.
The minimum down payment is 3.5% for borrowers with a credit score of 580 or higher, and gift funds from family can often be used.
FHA loans include an upfront and an annual mortgage insurance premium.
Best for: first-time buyers or anyone rebuilding credit or working with a smaller down payment.
Low or no down payment options for eligible veterans and service members.
Learn more +A VA loan is guaranteed by the U.S. Department of Veterans Affairs and is available to eligible veterans, active-duty service members, and some surviving spouses.
Eligible borrowers may be able to buy with no down payment, and VA loans don't require monthly private mortgage insurance.
A one-time VA funding fee usually applies, though some borrowers, such as those with a service-connected disability, may be exempt. You'll need a Certificate of Eligibility, which Greg can help you request.
Best for: those who have served and their families.
Low or no down payment options in eligible rural and suburban areas.
Learn more +A USDA loan is backed by the U.S. Department of Agriculture to help buyers in eligible rural and some suburban areas.
Eligible borrowers may be able to buy with no down payment. Household income limits apply, and the home must be your primary residence in an eligible area.
USDA loans include an upfront and an annual guarantee fee.
Best for: moderate-income buyers looking outside of major metro areas.
High-balance loans for premium properties.
Learn more +A jumbo loan is for loan amounts above the conforming loan limit set each year by the Federal Housing Finance Agency.
Because these loans can't be sold to Fannie Mae or Freddie Mac, they usually call for stronger credit, a larger down payment, and more cash reserves.
Best for: buyers of higher-priced homes in high-cost areas.
Finance the purchase and improvements in one loan.
Learn more +A renovation loan lets you finance a home and the cost of repairs or upgrades in one mortgage, based on the home's after-improvement value.
Common options include the FHA 203(k) and Fannie Mae HomeStyle programs, and they can be used to buy or refinance.
Best for: buying a fixer-upper or updating the home you already own without a separate loan.
Bank statement, 1099, and investor loans for borrowers who don't fit the standard paperwork.
Learn more +Not everyone fits the standard paperwork. Specialty and Non-QM (non-qualified mortgage) programs use other ways to verify your ability to repay.
Examples include bank statement loans for self-employed borrowers and DSCR loans for investors that qualify based on a property's rental income.
These programs may come with different rates, down payment, and credit requirements than traditional loans.
Best for: self-employed borrowers, business owners, and real estate investors.
Programs to help reduce cash to close.
Learn more +Down payment assistance programs can help cover your down payment or closing costs through grants, forgivable loans, or deferred second loans.
They're often run by state and local housing agencies, and each has its own income, purchase price, and homebuyer education requirements.
Best for: first-time and moderate-income buyers who need help with upfront cash.
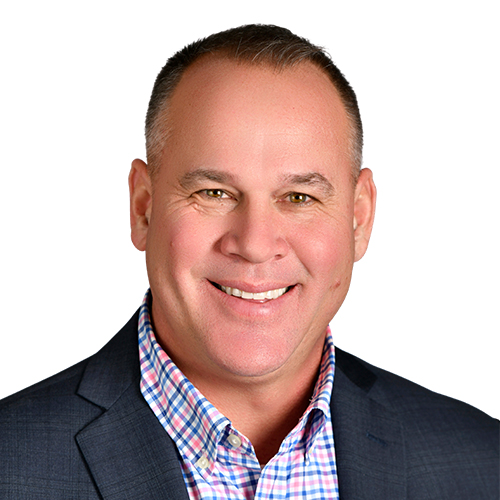
Before Greg Connors ever closed a loan, he spent seven years playing professional baseball in the Seattle Mariners organization. The game taught him preparation, discipline, and how to perform when it counts, and he brings that same approach to every mortgage he handles.
Greg has been in the mortgage business since 2003, with experience across retail, wholesale, and management. That range lets him handle the tough scenarios as well as the simple ones, whether that's a first-time buyer, a seasoned investor, a self-employed borrower, or a family looking to refinance.
His goal goes beyond a low rate. Greg builds a game plan around each client's long-term finances, explains every step in plain language, and keeps everyone informed from application to closing. Real estate agents, financial advisors, and accountants trust him with their clients for the same reasons.
Today Greg is a Producing Branch Manager with American Financial Network, leading Home Run Lending out of Miller Place, New York. He pairs a personal, coach-style relationship with AFN's nationwide lending platform and technology.
Greg lives in Mount Sinai with his wife and three kids. When he's not helping Long Island families get home, you'll find him on the golf course, out fishing, or cheering on the sidelines at soccer, volleyball and baseball games.
Mortgages Made Simple. Dreams Made Real.
5.0 rating from 24 client reviews on American Financial Network
“The team was good and kind. They really worked hard to ensure what we wanted. Communication was always upfront and clear.”
Elhadj N. · Bronx, NY
“Very efficient and easy to understand and on top of all the paperwork very friendly”
Joel A. · Port Jefferson Station, NY
“Great experience! Thanks for all of your help through the process. I look forward to working as a team again!”
Catherine T. · Port Jefferson Station, NY
Closed Fast & Smoothly
“He was knowledgeable, fast to respond, and genuinely cared about the thing he was telling us about. We couldn't have done this better without him.”
Jennifer N. · Verified Client
First-Time Buyer Success
“Gregory Connors was SO helpful in our whole home buying process and very thorough with everything! This was our first time buying a home and he was amazing.”
Emily G. · Verified Client
Saved Money Refinancing
“Gregory Connors did an outstanding job in assisting me throughout the entire loan process! I recommend Gregory Connors to anyone who is either looking to finance a new home or is looking to refinance!”
Thomas F. · Verified Client
Take the first step toward your new home. Start your pre-approval online, and Greg will walk you through every step.
Apply NowReach out today for a free consultation
Not ready to apply? Leave your info and Greg will reach out personally. There's no obligation.
Email: gconnors@afncorp.com
Phone: (631) 335-6451
Branch:
Home Run Lending
565 Route 25A, Suite LL2-A
Miller Place, NY 11764
Sophia is Greg's 24/7 AI mortgage assistant. Ask a question or get started any time, day or night.